From Your First Set of Keys to an Extraordinary Estate
Personalized buyer representation, property search, financing education and transaction guidance for every stage of homeownership throughout Arizona, Nevada and California.
First Home · Move-Up · Relocation · New Construction · Second Home · Luxury · Custom
Licensed in Arizona, Nevada and California. Nevada S.188993 · Arizona SA722354000 · California DRE 0214669
The positioning
Every buyer deserves a clear strategy—from the first home to the forever estate.
One relationship
One buyer strategy. Three states. Every level of homeownership — coordinated by a single licensed advisor.
Direct line
702-720-9911 · Marilena McAfee
Choose a Pathway and Your Buyer Plan Opens Pre-Set to It
Each pathway routes to the matching preparation, financing education and search strategy — and creates the appropriate CRM tags for follow-up.
I Am Buying My First Home
Readiness, financing, assistance resources and step-by-step guidance.
I Am Buying a Starter Home
Budget-conscious search, future resale considerations and ownership planning.
I Am Moving Up
Coordinate a current-home sale, purchase timing and a larger property.
I Am a Seasoned Buyer
Focused representation, streamlined search and transaction strategy.
I Am Relocating
Compare markets, tour remotely and organize a cross-state move.
I Am Buying New Construction
Compare builders, incentives, complete costs and timelines.
I Want to Build a Custom Home
Land, feasibility, architect, builder and construction pathway.
I Am Buying a Second Home
Lifestyle property, financing education, management and long-term considerations.
I Am a Luxury Buyer
Private search, discretion, elevated due diligence and lifestyle matching.
I Am an Ultra-Luxury Buyer or Representative
Authorized-representative communication, privacy, complex property and advisor coordination.
I Need to Sell Before I Buy
Coordinated listing and purchase timing, with the six routes compared.
I Am Not Ready Yet
A preparation roadmap — savings, credit education and timing, with no pressure.
I Am a Military or Veteran Buyer
VA-experienced lender introductions, PCS timing and remote purchase support.
Open the Specialty PageI Am an Athlete or Sports Professional
Privacy-conscious search, representative coordination and season-aware timing.
Open the Specialty PageI Am an Investor
Acquisition criteria, property analysis and independent professional coordination.
Open the Specialty PageTen Short Steps to Your Personalized Buyer Plan
Experience, purpose, markets, property type, needs, lifestyle criteria, financing status, timeline, current property, contact. Nothing here asks for financial documents.
Your preliminary roadmap
This roadmap is preliminary and based on the information provided. Financing and program eligibility require review by qualified lenders and program administrators.
Ready Now, Preparing Next or Planning Ahead — There Is a Path Forward
Understand the Complete Cost of the Loan — Not Just the Rate
Educational summaries only. No rates, no credit-score thresholds, no eligibility determinations. Program rules, limits and underwriting change; lender overlays vary. Qualification decisions belong to qualified lenders.
Sources: FHFA, HUD/FHA, U.S. Department of Veterans Affairs, USDA Rural Development, CFPB.
AgencyConventional Conforming
- The loan follows the applicable conforming parameters for the year, county and property type.
- Fixed and adjustable structures may be available.
- Down-payment and mortgage-insurance rules vary by program and lender.
- Qualification is determined by lenders, not by a real estate agent.
- County loan limits change annually.
Source: FHFA / the agencies
GovernmentFHA
- FHA insures qualifying loans made by approved lenders.
- May allow a lower down payment than some other programs.
- Mortgage-insurance premiums apply.
- Property and borrower requirements apply.
- Qualification must be confirmed by an FHA-approved lender.
Source: HUD / FHA
GovernmentVA
- For eligible service members, veterans and certain surviving spouses.
- VA does not require a down payment, though lenders may in some situations.
- No private mortgage insurance is required by VA.
- A funding fee may apply, with possible exemptions.
- Occupancy and property requirements apply.
- Eligibility and approval must be confirmed through the VA and qualified lenders.
Source: U.S. Department of Veterans Affairs — va.gov/housing-assistance
GovernmentUSDA
- Available for qualifying borrowers and eligible rural properties.
- Guaranteed and direct pathways differ.
- Income and property eligibility requirements apply.
- Qualified borrowers may have no-down-payment options.
- Availability must be confirmed through USDA and approved lenders.
Source: USDA Rural Development
Non-conformingJumbo
- Used when the loan amount exceeds the applicable conforming limits.
- Limits vary by year, county and property type.
- Underwriting standards vary by lender.
- Buyers may encounter greater liquidity, reserve, credit, appraisal and documentation requirements.
- Rates and costs may differ from conforming loans.
- Specialized jumbo and private-bank options should be compared.
Source: participating lenders
Lender productPhysician and Professional Programs
- Some lenders offer programs for qualifying physicians and other professionals.
- Terms, occupation eligibility and future-income treatment vary.
- These are lender products, not government programs.
- Marilena does not determine eligibility.
Source: participating lenders
Lender productBank-Statement and Non-QM Education
- Some lenders offer alternative-documentation programs.
- Rates, down payments, reserves and risks may differ.
- Non-QM does not mean no qualification.
- Independent lender and financial review is essential.
Source: participating lenders
TimingBridge or Buy-Before-You-Sell
- Potential options may include bridge loans, HELOCs, home-equity loans or specialized purchase programs.
- Qualification, collateral and repayment risk require lender review.
- Existing-home equity is not automatically accessible.
Source: participating lenders
BuildingConstruction and Construction-to-Permanent
- Used for certain custom-home and construction projects.
- May involve plans, builder approval, budgets, appraisals, draws and reserves.
- Program structure varies by lender.
Source: construction lenders
AssistanceDown-Payment Assistance
- Programs may be state, local, employer, nonprofit or lender administered.
- Income, property, occupancy, education, repayment and geographic requirements may apply.
- Some assistance is a grant; some may be deferred, forgivable or repayable.
- Program availability and funding can change.
- Eligibility requires confirmation from the program administrator and the lender.
Source: program administrators · directory adapter pending
No financingCash Purchase
- Cash removes financing-contingency considerations but does not eliminate due diligence.
- Proof of funds may be required.
- Inspection, title, insurance, appraisal and professional review may still be appropriate.
- Cash should not automatically be assumed to be the strongest offer in every situation.
Source: general practice
ComparisonRate Is One Line of Many
- Rate, APR, points, lender fees and mortgage insurance all affect total cost.
- Prequalification is a preliminary conversation; preapproval involves a lender's documented review.
- Lender overlays and underwriting standards vary between lenders on the same program.
- Compare official Loan Estimates side by side before choosing.
Source: CFPB — consumerfinance.gov
No single loan program is recommended universally. Marilena is a licensed real estate professional, not a lender, mortgage broker, credit-repair provider, financial advisor, CPA, tax advisor or attorney, and does not determine eligibility for any loan or assistance program.
Run the Numbers with Your Own Assumptions
Every figure below is entered by you or by your lender. Nothing here is a rate quote, a Loan Estimate, a prequalification or an approval.
Your First Home Should Begin with Education — Not Pressure
Preparation, lender comparison, representation, search, offer, due diligence, closing and the first year of ownership — in order, with nothing skipped and nothing rushed.
- 01PrepareCredit education through official resources, budget, savings and reserves.
- 02ConsultA buyer consultation: goals, process, timing and costs, start to finish.
- 03Speak with lendersTwo or more lenders, so programs and costs can be compared.
- 04Compare Loan EstimatesSide by side, on the official form — not on verbal quotes.
- 05Sign representation documentsScope, duration, coverage and compensation, in writing.
- 06Build property criteriaThe written property brief that drives every search.
- 07Search and tourOrganized tours, with notes and comparisons kept in one place.
- 08Prepare offerPrice, terms, contingencies and earnest money as one strategy.
- 09Complete due diligenceInspections, disclosures, HOA documents, title and insurance review.
- 10Finalize financingAppraisal, conditions and lender timelines, tracked to the date.
- 11CloseSigning, funding, recording and keys.
- 12Transition into ownershipMaintenance calendar, warranties, records and post-closing resources.
Search Homes Across Three States
The search connects to an approved MLS/IDX provider. Until that connection is live this page shows no inventory — fabricated listings are not displayed at any point.
Request a personalized property search. Complete your property brief and Marilena prepares a curated shortlist for you.
Criteria used to shortlist properties
Buyer actions on every property
Match the Home to the Life You Want to Live
Community Matching
Objective filters only, cross-referenced against your property brief and travel-time limits.
District links are provided as resources; districts, boundaries and programs must be verified independently.
Property Comparison
Up to five homes, side by side, on cost and condition — with no automatic winner selected.
Estimates are yours and your professionals'; the tool organizes them, it does not rank the homes.
Offer Strategy Lab
The strongest offer is not always the highest price — model price against terms.
Outputs a summary, cash needs, contingency review and the items needing lender or legal confirmation. No offer can be promised to win.
Inspection and Due Diligence
Property-specific checklists, assembled from the systems the home actually has.
Appropriate investigations depend on the property and the independent professionals you retain.
Fair Housing: community information is presented using objective criteria only. Areas and schools are never ranked as safest, best, good, bad or best-for-families, and no comparison is made on the basis of any protected characteristic. Buyers are encouraged to research communities, districts and properties independently. Equal Housing Opportunity.
Private Buyer Representation for Distinctive Properties
Discreet search strategy, elevated due diligence and lifestyle matching for luxury and ultra-luxury acquisitions — including purchases handled through authorized representatives, advisors and family offices. No claim is made to undisclosed or off-market inventory.
Brief fields
Security details, staff information and travel patterns are never collected through a public form.
Coordinated services
- Private search strategy and property previews
- Public and authorized private inventory review
- Remote video review and architectural comparison
- Jumbo and private-bank lender introductions
- Entity and trust coordination with your attorneys
- Insurance review and specialty inspections
- Appraisal planning for complex properties
- Art, furnishings and specialty-property coordination
- Custom-home and land pathway
- Privacy-conscious showing arrangements
- Security-professional coordination through your own team
- Moving and household-resource referrals
International buyers
Cash and foreign-national financing pathways through qualified lenders, entity ownership coordinated with your attorneys and tax professionals, remote transaction and signing logistics, title and escrow, insurance and property management. Immigration, legal, tax and currency advice is outside the scope of real estate services.
Production, Quick Move-in, Semi-Custom or Fully Custom
Builder and incentive comparison, complete-cost planning beyond the base price, design-center strategy, construction timeline and independent inspection planning.
Before you register: builder registration policies vary. Contact Marilena before registering online, calling or visiting a sales center so representation options can be reviewed.
Coordinate the Sale and the Purchase as One Plan
Six routes, compared on cash-flow overlap, timing risk and convenience:
- Sell first — Maximum certainty of funds; you may need temporary housing.
- Buy first — Move once; requires lender review of carrying both properties.
- Simultaneous closing — Tightly coordinated dates; least slack in the schedule.
- Contingent purchase — Offer strength depends on the market and the seller's position.
- Temporary housing and storage — Bridges a timing gap; adds a move and monthly cost.
- Bridge or equity consultation — Lender-reviewed only — existing equity is not automatically accessible.
Buying Across State Lines, Remotely
Market comparison across Arizona, Nevada and California, remote consultations, video property review, community orientation, travel planning, temporary housing and settling-in resources — one advisor for all three states.
Relocation PathwayCompare Three States from One Strategy
Arizona
Scottsdale and Paradise Valley through the East and West Valley and into Pinal County — production and custom new construction, golf and gated communities, active-adult and multigenerational homes.
Nevada
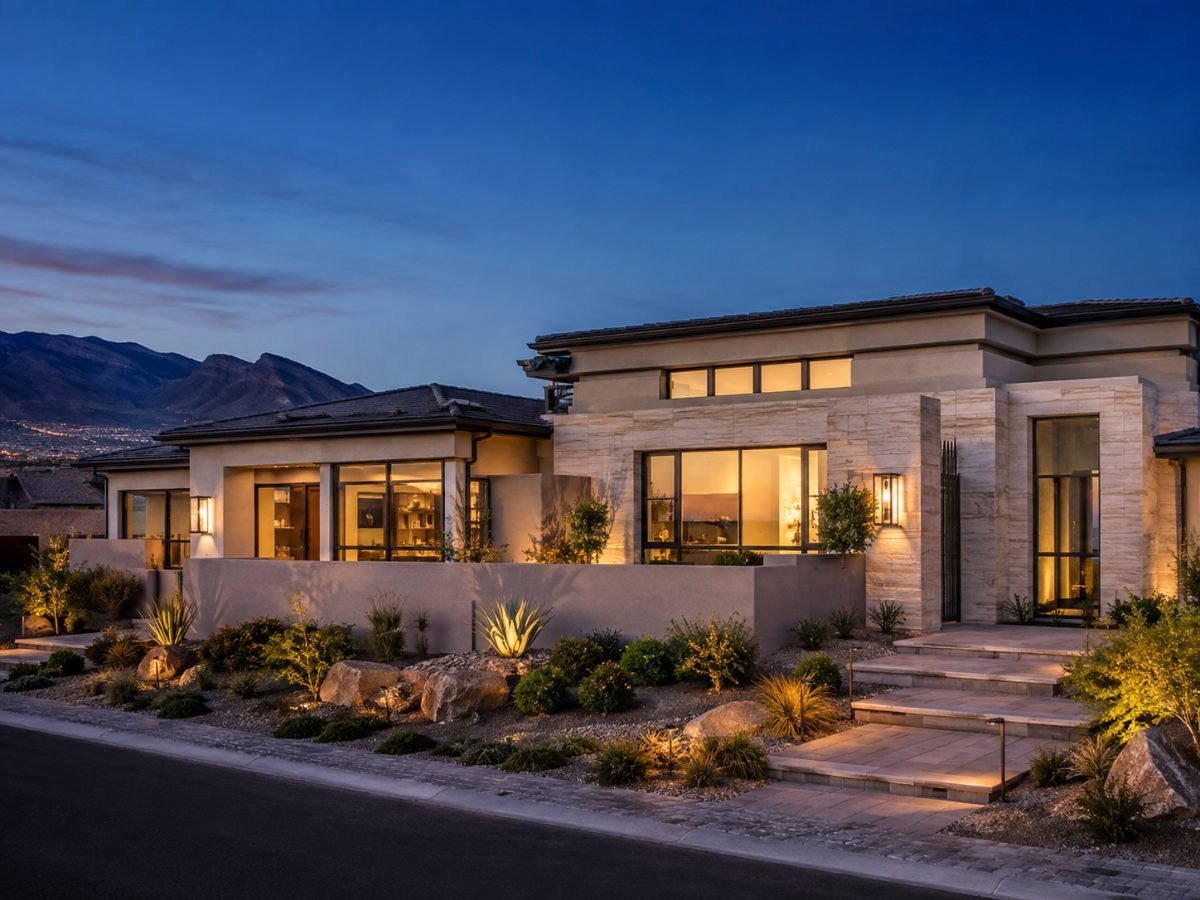
Las Vegas, Henderson and Summerlin, the master-planned southwest, and the guard-gated communities — from first homes to MacDonald Highlands and Lake Las Vegas.
California
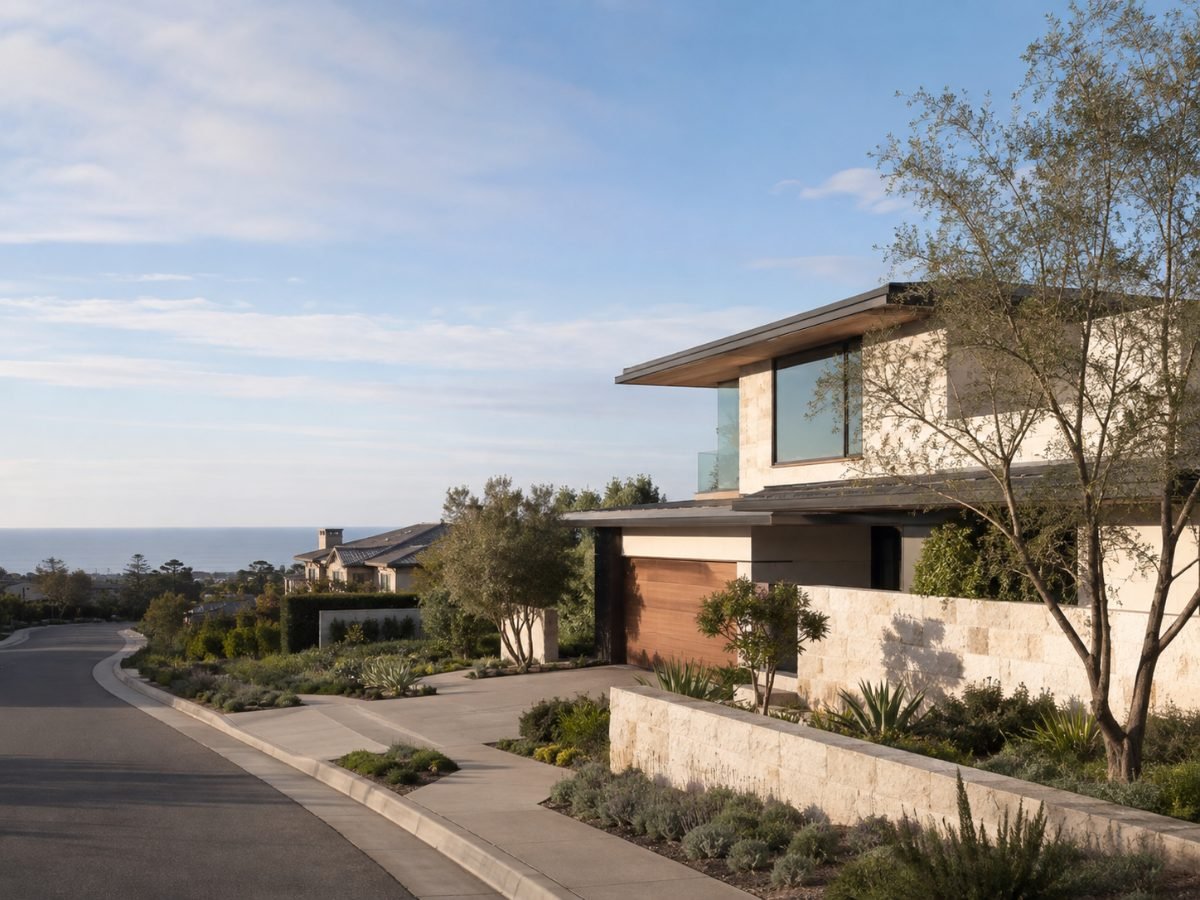
Greater Los Angeles, the South Bay and valleys, Orange County, the Inland Empire and San Diego County — coastal property, condominiums and estates, with qualified referral coordination where appropriate.
The Listing Agent Represents the Seller. Your Representation Should Be Clear Too.
What a written buyer agreement addresses
- The agency relationships available in your state and what each means
- A written buyer agreement: services, duration and geographic coverage
- How broker compensation is set, and that it is negotiable
- Potential seller or builder contributions, and that none is guaranteed
- Buyer obligations during the agreement
- Dual agency or limited representation, where permitted
- Confidentiality of your information and your criteria
- Termination provisions
- The questions worth asking before you sign anything
Real estate services are not free. Broker compensation is negotiable, must be addressed in a written buyer-representation agreement, and may be paid by the buyer, seller, builder or another permitted source. It may be negotiated within an offer, is not guaranteed to be paid by another party, and the buyer may be responsible for an agreed difference. Agency rules and disclosures differ in Arizona, Nevada and California; your brokerage's state-specific forms govern.
The ten-step buyer process
Your Search, Decisions and Transaction — Organized in One Place
Private buyer workspace—features and availability may vary. Access is issued individually after consultation; no unsecured public portal is published, and documents move through the secure document system rather than this page.
Independent referral network
All providers are independent third parties. Marilena coordinates introductions only; each provider must be evaluated, engaged and paid by the buyer directly.
The Complete Arizona, Nevada & California Homebuyer Guide
Choose the modules that match your purchase and the guide is assembled for you — readiness through post-closing ownership, with the state sections you actually need.
Selected: First-time buyer.
Meet Your Buyer Advisor
Marilena McAfee is a real estate professional licensed in Nevada, Arizona and California. Her background includes residential and commercial real estate, transaction coordination, property operations, relocation, new construction and client service.
Through Real Estate by Marilena, she helps buyers move from preparation and market comparison through property selection, negotiation, due diligence, closing and relocation—whether purchasing a first home, moving between states, building new or acquiring a distinctive luxury property.
Nevada S.188993 · Arizona SA722354000 · California DRE 0214669 · 702-720-9911
The service standard
- Personalized buyer roadmap
- Written property brief
- Market and community comparison
- Financing-resource coordination
- Curated property recommendations
- Organized tours
- Property comparison
- Offer strategy
- Inspection and due-diligence planning
- Transaction milestone updates
- New-construction guidance
- Sell-and-buy coordination
- Privacy-conscious communication
- Post-closing resources
- No public use of client identity without permission
Questions, Answered Plainly
Do I need 20% down?
No single down-payment figure applies to every buyer or program. Requirements vary by loan program, property type, occupancy and lender, and mortgage insurance may apply below certain equity levels. A lender can tell you what your options require.
What is the difference between prequalification and preapproval?
Prequalification is generally a preliminary conversation based on information you state. Preapproval generally involves a lender's documented review. Neither is a loan commitment, and processes differ between lenders.
Can you tell me what I can afford?
No — that is a lender's determination. The planning tools here let you model payments and cash needs with your own assumptions so you can have a better conversation with lenders.
What are closing costs and cash to close?
Closing costs are the fees and charges to originate and close the loan and transfer the property. Cash to close also includes your down payment and prepaid items, less any credits and earnest money already paid. Your Loan Estimate states these figures.
What is APR, and what are points?
APR expresses the cost of credit as a yearly rate reflecting certain fees, not just the interest rate. Points are charges paid at closing that may affect the rate. Both belong in a side-by-side comparison of official Loan Estimates.
Should I compare lenders?
Comparing official Loan Estimates from more than one lender is generally advisable. Program pricing, fees, credits and overlays differ between lenders on the same loan type. The comparison tool on this page is built for exactly that.
What are conforming loan limits?
Limits published annually for conforming loans, varying by year, county and unit count, with higher limits in designated high-cost areas. Limits do not determine whether a borrower is approved.
How is a buyer's agent compensated?
Compensation is negotiable and must be addressed in a written buyer-representation agreement. It may be paid by the buyer, seller, builder or another permitted source, may be negotiated within an offer, and is not guaranteed to be paid by another party — the buyer may owe an agreed difference.
Can the seller pay my closing costs?
A seller or builder contribution can be requested in an offer, and loan programs cap what may be applied. Nothing about a contribution is guaranteed; it is a negotiated term.
Can I buy before selling?
Sometimes — through a contingent purchase, a simultaneous closing, temporary housing or lender products such as bridge financing. Which route fits depends on your equity, the lender's review and the market. The sell-and-buy planner compares them.
When should I contact a builder?
Before registering online, calling or visiting a sales center. Builder registration policies vary and can affect representation options, so let's talk first.
What inspections should I obtain?
That depends on the property and the professionals you retain — general, roof, sewer scope, septic, well, pool, solar, structural, termite, environmental, HOA document and title review are all possibilities. We plan them property by property.
What happens if the appraisal is low?
Options may include renegotiation, additional funds, an appraisal reconsideration process where available, or exercising a contract right. Appraisal outcomes cannot be predicted or promised.
What is earnest money?
A deposit submitted with or shortly after an accepted offer, held per contract, generally credited at closing. Whether it is refundable depends on the contract's contingencies and deadlines.
Can you help remotely, and across all three states?
Yes — Marilena is licensed in Arizona, Nevada and California and works with remote and relocating buyers through video property review, remote consultations and coordinated travel.
What happens after I complete the buyer plan?
You receive a preliminary roadmap, and Marilena follows up to confirm the property brief, arrange the consultation and, where requested, introduce independent lenders.
Every Great Purchase Begins with a Clear Buyer Strategy
Licensed in Arizona, Nevada and California. Schedule a consultation.